608: THE EVOLVING AVIATION MRO INDUSTRY AND INDIA’S OPPORTUNITY


My article was published in the Mar 25 issue of Life of Soldier Journal.


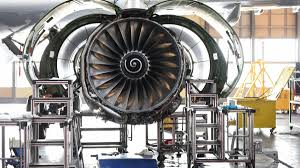
India’s aviation Maintenance, Repair, and Overhaul (MRO) market is witnessing rapid growth, driven by increasing air travel demand, expanding airline fleets, and government initiatives promoting domestic MRO services. As airlines seek cost-effective maintenance solutions, India’s strategic location and skilled workforce position it as a potential global MRO hub. However, high taxation, infrastructure gaps, and regulatory hurdles hinder its full potential. With policy reforms, investment in advanced facilities, and collaboration with global players, India can transform its MRO sector into a key driver of the aviation industry. This article explores India’s MRO market’s growth, challenges, and opportunities.


Key Players in the Aviation MRO Industry


The Aviation Maintenance, Repair, and Overhaul (MRO) industry comprises airlines, independent MRO providers, Original Equipment Manufacturers (OEMs), and specialised component repair firms. These entities offer a wide range of services, from routine maintenance to complex overhauls, ensuring the safety and reliability of aircraft worldwide.


Airlines with In-House MRO Capabilities. Many airlines operate MRO divisions to maintain their fleets and offer third-party services. Lufthansa Technik, a subsidiary of Lufthansa Group, is one of the largest MRO providers globally, offering airframe maintenance, engine services, and component support. Similarly, Delta TechOps, the MRO arm of Delta Air Lines, provides maintenance services for Delta’s fleet and other airlines. Another major player, Air France Industries KLM Engineering & Maintenance (AFI KLM E&M), services various aircraft and engines, offering component maintenance and logistics support.


Independent MRO Providers. Independent MRO companies operate globally, serving airlines and aircraft operators. ST Engineering Aerospace, based in Singapore, provides airframe, engine, component maintenance, and cabin refurbishments. AAR Corp, a U.S.-based provider, offers component repair, logistics, and airframe maintenance for commercial and defence sectors. HAECO (Hong Kong Aircraft Engineering Company Limited) specialises in airframe maintenance, component services, and cabin solutions.


Original Equipment Manufacturers (OEMs). OEMs have expanded into the MRO sector to support their aircraft and components. Boeing Global Services offers maintenance, parts, and digital solutions for Boeing aircraft. Airbus Services provides technical support and training for Airbus operators, focusing on predictive maintenance. GE Aviation specialises in engine MRO services, offering maintenance solutions for both its own and other manufacturers’ engines. Rolls-Royce TotalCare provides comprehensive engine maintenance under long-term service agreements.


Specialised Component and Engine MRO Providers. Several companies focus on specific components and engines. MTU Aero Engines, based in Germany, provides engine MRO services for commercial and military aircraft. StandardAero offers engine and airframe MRO services for commercial and business aviation. SIA Engineering Company, based in Singapore, partners with multiple OEMs to enhance its service offerings.


Regional MRO Providers. Many regional providers cater to specific markets. Turkish Technic offers airframe, engine, and component maintenance and aircraft modifications. Joramco, based in Jordan, provides airframe and component maintenance for various aircraft. GAMECO (Guangzhou Aircraft Maintenance Engineering Company), a Chinese MRO provider, specialises in airframe, component, and engine services.


Emerging and Niche Players. Smaller MRO providers are expanding their presence. Based in Estonia, Magnetic MRO provides line and base maintenance, engineering, and asset management services. FL Technics, a European-based provider, offers line and base maintenance and component support, primarily serving airlines in Europe, Asia, and the CIS region.


Digital and Data-Driven MRO Service Providers. Digital transformation is reshaping the MRO industry. Based in Switzerland, SR Technics integrates digital solutions and data analytics for predictive maintenance. Lufthansa Technik’s Aviatar platform provides predictive maintenance and technical asset management to improve operational efficiency.


Collaborative Ventures and Alliances. Partnerships between MRO providers and OEMs enhance service capabilities. AFI KLM E&M and Boeing collaborate to provide component support and maintenance solutions for Boeing 787 aircraft. TAP Maintenance & Engineering partners with OEMs to improve its servicing capabilities.


Aviation Maintenance, Repair, and Overhaul (MRO) India


India’s aviation sector is expanding remarkably, positioning the country as one of the largest aviation markets in the world. With rising air travel demand, the MRO industry is expected to witness significant growth, projected to reach a value of around $1 billion by 2025. The increasing number of domestic and international flights, the rise of low-cost carriers, and the burgeoning middle class are major contributors to this growth. Airlines are prioritising maintenance and repair services to ensure operational efficiency and safety.


Key Indian Players. Several key players dominate the Indian MRO industry, each contributing to its development. Air India Engineering Services Limited (AIESL), a subsidiary of Air India, provides comprehensive MRO services for both Air India and third-party airlines, offering airframe maintenance and component support. The Indira Gandhi Institute of Aeronautics (IGIA) plays a crucial role in workforce training through its partnerships with airlines and MRO providers. GMR Aero Technic, a part of the GMR Group, operates from Hyderabad and offers maintenance, repair, and overhaul services. Hindustan Aeronautics Limited (HAL), a state-owned entity, specialises in aircraft maintenance, particularly for military aircraft. The TATA Group has entered the MRO sector through TATA Advanced Systems, focusing on military and commercial aircraft maintenance.


Challenges Faced by the MRO Industry in India. Despite its promising growth, the Indian MRO sector faces several challenges. Infrastructure development remains a significant issue, as many MRO facilities require upgrades to meet global standards. The industry also suffers from a shortage of skilled technicians and engineers, necessitating targeted efforts to attract and train talent. High import duties on aircraft spare parts increase costs for MRO providers, making it challenging to source necessary materials at competitive rates. Additionally, navigating complex regulatory compliance requirements can be resource-intensive for MRO operators. The following factors collectively hamper the growth of an indigenous MRO industry, making Indian airlines reliant on foreign facilities for maintenance.


    • OEM Aftermarket Monopoly. Original Equipment Manufacturers (OEMs) dominate the aftermarket, restricting independent MRO players through intellectual property (IP) control, high consultancy fees, and restrictions on direct part sales. OEMs also use pricing strategies and exclusive contracts to limit competition.
    • Contractual & Offset Clause Issues – Airlines and OEMs impose conditions in aircraft purchase/leasing deals, such as mandatory maintenance at designated (often foreign) MRO facilities. Offset clauses, especially in defence aviation, usually remain unimplemented, limiting local MRO capabilities.
    • Infrastructure Shortcomings. Limited land allocation for airport MRO hangars increases logistics costs. Training infrastructure is also inadequate, with many institutes lacking access to aircraft for hands-on learning.
    • Lack of Access to Credit. MRO is capital-intensive, and post-pandemic financial strains have made credit access difficult. High collateral demands further restrict expansion.
    • Post-pandemic Demand-Supply Mismatch. While India anticipated MRO growth, post-2021 tax reforms, oversupply due to global pandemic disruptions, and supply chain constraints had hindered expected expansion.
    • Taxation & Duty Issues. Despite the reduction of GST on MRO services, high tax rates on spare parts deter growth. Complex customs classifications also result in excessive duties, while the inverted duty structure discourages local manufacturing. Additionally, Indian airports charge royalties on MRO revenue, increasing operational costs.


Emerging Trends. Several emerging trends are shaping the future of the Indian MRO industry. The government has proactively supported this sector through initiatives like the National Civil Aviation Policy and the “Make in India” campaign, which encourage domestic manufacturing and services. Digital transformation is another key trend, with MRO providers increasingly leveraging data analytics and IoT to improve operational efficiency and predictive maintenance. Indian companies are also forming partnerships with global MRO players, gaining access to advanced expertise, technology, and best practices to enhance service quality.


Future Prospects. Looking ahead, the future of the Indian MRO industry appears promising. The continuous rise in air traffic is expected to drive sustained demand for maintenance services, creating new opportunities for existing players and new entrants. Investment opportunities abound in MRO facilities, workforce development, and advanced technologies. As India continues to cement its position as a key player in the global aviation market, strategic initiatives from government and private sector investments will likely shape a more robust and competitive MRO industry.


Recommendations for Strengthening India’s MRO Sector. Key challenges must be addressed to enhance India’s Maintenance, Repair, and Overhaul (MRO) industry and make it competitive globally. The sector needs investment, regulatory support, and improved infrastructure. The following short-term and long-term measures are recommended.


    • Establish a Nodal Agency for MRO Regulation. A dedicated regulatory body should oversee policies, manage inter-ministerial coordination, and implement industry reforms. The agency should promote technological innovation (AI, predictive analytics, drones) and encourage R&D for indigenous technology. Offset management must ensure foreign investments contribute to capacity and technology development. Efforts should be made to expand India’s global MRO outreach and foster strategic partnerships with OEMs. Strengthen human resource development through industry-academia collaborations and international exchange programs.
    • Leverage low-IP-control areas as Entry Points. Indian MRO should focus on line maintenance, structural repair, avionics, and electrical work before progressing to high-IP areas like engine maintenance. Partnering with Tier-I global MROs can expand expertise and market reach.
    • Develop Infrastructure and Encourage OEM Collaborations. Self-sufficiency in spare parts manufacturing is crucial, as spares constitute 55% of component MRO and 80% of engine MRO costs. Government support through Production Linked Incentives (PLI) and joint ventures with FAA/EASA-certified MROs can boost domestic production.
    • Address OEM Monopoly and Strengthen Alternatives. OEMs dominate aircraft maintenance through restrictive contracts and data control. India should promote alternatives like Surplus Parts (Used Serviceable Materials), Designated Engineering Representatives (DER) Repairs, and Parts Manufacture Approval (PMA). India should seek bilateral agreements to promote global acceptance of DGCA certifications.
    • Introduce Capital Investment Incentives. The government should offer tax credits on capital expenditures, PLI incentives for components and spares, lower duties/taxes on Indian-made aviation parts, and state-level incentives for electricity and amenities to attract foreign MRO investments.
    • Adopt a Public-Private Partnership (PPP) Model. MRO facilities require high capital investment and long break-even periods. Government-owned, Privately Operated (GOPO) models can optimise public MRO capacities like AIESL and HAL.
    • Civil-Defence MRO Convergence. Leverage underutilised defence MRO capacity (e.g., HAL) to support civil aviation needs. Absorb skilled defence personnel into the civil MRO workforce.
    • Rationalise Customs Duty, GST, and Land Rentals. Reduce high GST and customs duty on aircraft parts to match competitors like Malaysia and Singapore. Extend duty exemptions to MRO-imported aircraft parts. Lower AAI land lease rentals to make MRO operations cost-effective.
    • Enhance Human Capital Development. Establish industry-linked aviation training programs. Government-supported scholarships and exchange programs can create a skilled workforce.
    • Recognise MRO as Infrastructure. Including MRO services in India’s Harmonized Master List of Infrastructure Sub-sectors will enable tax benefits, foreign investment, and financial incentives.


Conclusion

India’s aviation MRO market is poised for significant expansion, driven by rising air traffic, government initiatives, and cost advantages. However, challenges such as high taxation, regulatory complexities, and infrastructure gaps hinder its full potential. India must streamline policies, enhance local capabilities, and attract global investments to capitalise on opportunities. Strengthening the domestic supply chain and fostering skilled labour will further boost competitiveness. With strategic reforms and industry collaboration, India can emerge as a global MRO hub, reducing dependence on foreign facilities and fostering self-reliance. The sector’s growth is vital for the broader aviation ecosystem, supporting economic development and technological advancement.


Please Do Comment.


2113
Default rating

Please give a thumbs up if you  like The Post?


For regular updates, please register your email here:-

Subscribe


References and credits

To all the online sites and channels.

Pic Courtesy: Internet

References:-

  1. Ministry of Civil Aviation, Government of India. (2023). National Civil Aviation Policy (NCAP). Retrieved from https://www.civilaviation.gov.in
  1. Directorate General of Civil Aviation (DGCA). (2023). Annual Report on Indian Aviation Sector. Retrieved from https://www.dgca.gov.in
  1. Invest India. (2023). India’s MRO Industry: Growth Potential & Investment Opportunities. Retrieved from https://www.investindia.gov.in
  1. NITI Aayog. (2022). Aviation Sector Development: Roadmap for 2030. Retrieved from https://www.niti.gov.in
  1. Federation of Indian Chambers of Commerce & Industry (FICCI). (2023). Indian MRO Industry: A Gateway to Self-Reliance.
  1. CAPA India. (2023). Indian Aviation Outlook: MRO Market and Capacity Growth.
  1. Sharma, R., & Verma, A. (2022). “Economic Viability of MRO Operations in India.” Journal of Air Transport Studies, 15(3), 145-167.
  1. Patel, N., & Iyer, M. (2021). “Assessing Policy Reforms in Indian Aviation Maintenance Sector.” Aerospace Industry Review, 9(4), 223-240.
  1. Gupta, P. (2020). “Infrastructure Challenges for India’s MRO Industry.” International Journal of Aviation Management, 7(2), 78-95.
  1. The Economic Times. (2023, October 15). “India’s MRO Industry Set for $5 Billion Expansion.” Retrieved from https://economictimes.indiatimes.com
  1. Business Standard. (2023, November 10). “MRO Reforms: Will India Reduce Dependence on Foreign Maintenance Hubs?” Retrieved from https://www.business-standard.com
  1. Aviation Week. (2023, December 5). “India’s Emerging Role in Global Aircraft Maintenance.” Retrieved from https://www.aviationweek.com
  1. Live Mint. (2023, September 20). “Budget 2023: Tax Cuts & Incentives to Boost India’s MRO Sector.” Retrieved from https://www.livemint.com
  1. Interview with Amber Dubey, Former Joint Secretary, Ministry of Civil Aviation. (2023). Discussing policy reforms for India’s MRO sector. Published by FICCI Aviation Summit Proceedings.

Disclaimer:

Information and data included in the blog are for educational & non-commercial purposes only and have been carefully adapted, excerpted, or edited from reliable and accurate sources. All copyrighted material belongs to respective owners and is provided only for wider dissemination.
 

604:TECHNOLOGY HARVESTING BY INDIAN AEROSPACE INDUSTRY: A STRATEGIC IMPERATIVE


My article published on the Indus International Research Foundation website on 19 Feb 25.


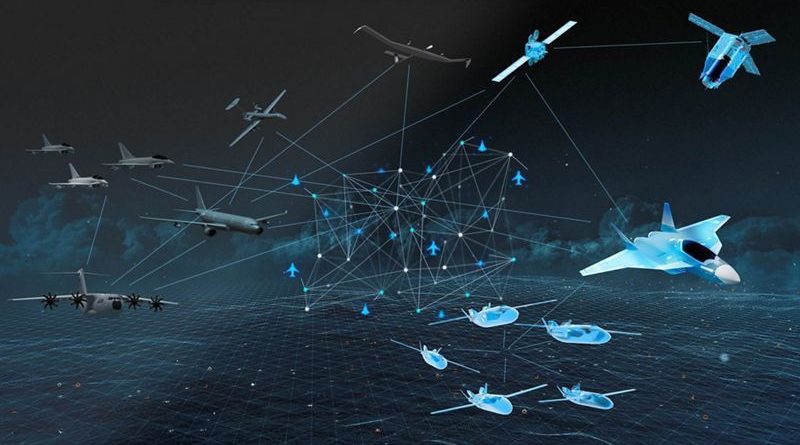
The Indian aerospace industry has made significant strides in technology harvesting, particularly in defence, satellite technology, and aircraft development. Key successes include the development of indigenous fighter jets like the HAL Tejas and the successful launch of ISRO satellite missions, such as the Mars Orbiter Mission. These achievements demonstrate the growing capability of India’s aerospace sector in adopting advanced technologies and adapting them to local needs. However, there are notable misses, primarily in producing high-performance engines and strategic aerospace systems, where India still relies heavily on imports. Despite efforts to indigenous technology, challenges like bureaucratic inefficiencies, limited R&D funding, and a lack of skilled workforce hinder complete technological independence. The industry must address these gaps through improved collaboration, investment in cutting-edge research, and focused policy support to achieve self-reliance and compete globally in the aerospace sector.


Technology Harvesting: The Process.


Technology harvesting refers to acquiring, utilising, and leveraging existing or newly developed technologies to achieve strategic goals, enhance innovation, or create value. This practice can involve various methods, such as sourcing new technologies, adapting existing ones, commercialising them, or repurposing them for different industries or applications. Technology harvesting often aims to advance an organisation’s capabilities, improve productivity, maintain a competitive edge, or create new products and services. It can involve the following:-


    • Identifying valuable technologies. Finding technologies that can benefit a company’s growth or strategic advantage.
    • Acquiring technologies. Through means like acquisitions, licensing, or partnerships.
    • Commercialising or adapting technologies. Transforming acquired technologies into profitable products, services, or processes.
    • Maximising the utility of available technologies. Making the most of existing technological assets by integrating them into new contexts or markets.


Ways and Means. Numerous methods help businesses and organisations stay competitive by quickly accessing and implementing new technologies. Some of these are:-


    • Internal Research and Development (R&D). Companies and organisations invest in R&D to develop new technologies that can give them a competitive edge. This can be through in-house teams or dedicated innovation labs.
    • Collaborative Research and Development (R&D). Partnerships between universities, research institutes, and businesses allow for technology sharing and joint development, which can expedite innovation.
    • Buying Start-ups: Larger companies often acquire smaller tech start-ups that have developed innovative technologies. This enables quick access to cutting-edge tech and talent.
    • Technology Transfer. Institutions like universities often transfer their research outputs to private companies that can commercialise the technology. This is facilitated through licensing agreements.
    • Technology Licensing. Companies or individuals who hold patents on specific technologies can license them to other firms for a fee or a royalty agreement.
    • Patent Pools. Multiple organisations might collaborate and share patents or licenses to reduce barriers and avoid litigation, accelerating technology adoption.
    • Open-source software. Companies or individuals contribute to open-source projects, allowing others to use, modify, and build upon the technology freely. This can lead to rapid advancement and broader adoption.
    • Open Innovation. Engaging external parties in solving technological challenges, including crowdsourcing solutions and using external ideas and inventions to advance a product or service.
    • Tech Incubators. These programs support early-stage start-ups by providing resources like mentorship, capital, and networking opportunities to help turn nascent technologies into viable businesses.
    • Accelerators. Accelerators are similar to incubators but focus on scaling and rapidly bringing technologies to market. These programs often have a more structured approach.
    • Joint Ventures. Companies often form joint ventures to combine resources and technologies, enabling both parties to leverage each other’s expertise.
    • Industry Collaborations. Corporations in the same industry may collaborate to develop shared technologies that benefit all parties involved.
    • Product Disassembly. Some organisations or individuals harvest technology by disassembling a competitor’s product to understand its design and function. While legally risky, this can provide insights into innovation.
    • Crowdfunding Platforms. Companies and inventors can raise funds to bring their technologies to market by directly engaging with the public. Popular platforms like Kickstarter or Indiegogo can help gauge market interest.
    • Crowdsourcing Ideas. Platforms like InnoCentive allow companies to post problems and offer rewards for solutions, enabling the harvesting of global ideas and innovations.
    • Scanning for Emerging Tech. Firms often employ technology scouts to search for new technologies that could be adopted, licensed, or acquired. This involves monitoring patent filings, academic publications, and industry trends.
    • Subsidies and Funding. Governments often provide grants and funding to develop or commercialise new technologies, particularly in fields like green energy, biotechnology, or defence.
    • Public-Private Partnerships. Governments may partner with the private sector to develop key technologies and infrastructure projects.


Indian Aerospace Industry and Technology Harvesting


The Indian aerospace industry has undergone a significant transformation in recent decades, shifting from a sector heavily reliant on imports to one that is making substantial progress in indigenous development. This evolution has been primarily driven by government initiatives, defence collaborations, foreign investments, and, most notably, technology harvesting.


Evolution of the Indian Aerospace Industry. The foundation of India’s aerospace industry was laid in the early 1940s with the establishment of Hindustan Aircraft Limited (now Hindustan Aeronautics Limited, HAL). Over the years, the Indian government, through organisations such as DRDO (Defence Research and Development Organisation), ISRO (Indian Space Research Organisation), and private-sector initiatives, has fostered aerospace capabilities. Despite significant progress, India still relies heavily on imported technology, particularly in critical areas such as jet engines, avionics, and stealth technology.


Technology Harvesting in the Indian Aerospace Industry. Technology harvesting has played a crucial role in advancing India’s aerospace capabilities. The country employs multiple strategies to acquire and integrate advanced technology, including technology transfer agreements, joint ventures, back engineering, and indigenous R&D.


    • Technology Transfer. India has effectively utilised offsets and technology transfer agreements in defence procurement deals as a key strategy for technology harvesting. These agreements, which mandate foreign firms to invest a portion of the contract value in India’s defence sector, have fostered local expertise and infrastructure development. For instance, the Rafale Deal with Dassault Aviation, France, involves the transfer of advanced radar, avionics, and composite material manufacturing techniques to Indian firms. Similarly, India’s partnerships with Boeing and Lockheed Martin have led to the domestic manufacturing of C-130J Super Hercules airframes and Apache attack helicopter components.
    • Joint Ventures. The Indian government has encouraged joint ventures between domestic and foreign companies to accelerate technology harvesting. These partnerships allow Indian firms to access cutting-edge aerospace technology while contributing to global supply chains. Notable joint ventures include Tata Advanced Systems and Lockheed Martin for manufacturing C-130J Super Hercules airframes in India, Adani and Elbit Systems (Israel) for UAV production under the “Make in India” initiative, and L&T and ISRO Collaboration for developing reusable launch vehicles and space technologies.
    • Indigenous Aerospace Programs and Achievements. Technology harvesting has significantly influenced India’s ability to develop indigenous aerospace programs. The success of these programs is a testament to India’s growing self-reliance in the sector.


Successes


India’s aerospace industry has made significant strides in technology development over the past few decades, particularly in indigenous aircraft production, space exploration, and defence technology. Here’s a look at its notable successes and challenges.


Indigenous Aircraft Development. One of the achievements is the development of the HAL Tejas, a fourth-generation multi-role light combat aircraft.  The Tejas has proven successful in designing, engineering, and integrating advanced systems, though it still faces some challenges related to production timelines and numbers.


Space Technology. ISRO (Indian Space Research Organisation) has shown significant technological advances, especially in satellite technology and space exploration. India’s Mars Orbiter Mission (Mangalyaan) and Chandrayaan missions to the Moon were notable successes, signalling India’s growing expertise in space missions.


GSLV & PSLV Rockets. India has developed reliable launch vehicles, particularly the Polar Satellite Launch Vehicle (PSLV), making India one of the leading providers of commercial satellite launches globally. The Geosynchronous Satellite Launch Vehicle (GSLV) has been crucial for launching heavier payloads, demonstrating a significant leap in India’s rocket development.


Missile Technology. India’s missile technology, mainly through the Agni and Prithvi series, has significantly succeeded in strategic and tactical weapons. The BrahMos, a joint venture with Russia, is among the world’s fastest cruise missiles and showcases India’s ability to partner internationally while developing cutting-edge technology.


Hypersonic and Space Technologies. India is making strides in hypersonic technology, a critical frontier in aerospace innovation. The Hypersonic Technology Demonstrator Vehicle (HSTDV), developed by DRDO, is a significant step toward mastering scramjet propulsion for future hypersonic missiles and aircraft.


Challenges.


Delays in Aircraft Production. While successful, the HAL Tejas program has faced significant delays. Initially expected to enter service in the late 1990s, the Tejas project has been plagued by issues related to engine integration, production delays, and insufficient numbers for the Indian Air Force (IAF).


Missed Opportunities in Commercial Aircraft Manufacturing. India has failed to develop a competitive indigenous commercial aircraft. The RTA-70 was initially conceived as a regional aircraft but has not progressed beyond the conceptual stages. HAL’s failure to enter the commercial aircraft market has kept India from tapping into a potentially lucrative market, especially with rising demand for air travel in Asia.


Reliance on Foreign Technology. While India has made strides in many defence technologies, it remains heavily dependent on foreign technology for critical components, such as aircraft engines, avionics, and radar systems. The Kaveri engine, developed for the Tejas, faced performance issues, leading to continued reliance on foreign suppliers like GE Aviation for the Tejas’ engine. Similarly, radar and electronic warfare systems are often imported.


Slower Transition to 5th Generation Aircraft. India’s pursuit of a fifth-generation aircraft, specifically the AMCA (Advanced Medium Combat Aircraft), has been slow. While it is an ambitious project, it faces development timelines and funding challenges. Additionally, India’s slow progress in stealth technology has led to delays compared to countries like China and Russia, which are already advancing.


Challenges in Commercial Space. While ISRO has achieved remarkable success in government and scientific space exploration, it has not yet fully capitalised on the commercial space sector. Although India has been a competitive player in satellite launches, it faces stiff competition from U.S. and European private companies. The growth of private space players like SpaceX has overshadowed ISRO’s commercial potential in the global space race.


Way Ahead

The way ahead for technology harvesting by the Indian aerospace industry lies in a multi-pronged approach, focusing on leveraging global innovations, fostering indigenous capabilities, and enhancing collaboration between government, private sector, and academia. India has historically depended on technology imports to meet the demands of its aerospace sector. Still, with growing aspirations for self-reliance, the industry is actively working on increasing its technological base. A significant step in this direction is the Indian government’s push for the “Atmanirbhar Bharat” (Self-reliant India) initiative, which encourages domestic manufacturing and innovation.


Key areas for technology harvesting include advanced materials, propulsion systems, avionics, and unmanned aerial vehicles (UAVs). Collaboration with global aerospace leaders and partnerships with foreign entities through joint ventures and knowledge exchange programs will enable the Indian aerospace sector to integrate cutting-edge technologies. The private sector’s growing role, exemplified by companies like Tata Advanced Systems and Reliance Aerospace, is crucial in driving innovation and attracting foreign direct investment. These companies are now working to develop advanced systems and technologies that could be exported globally. Additionally, academia and research institutions like the Indian Space Research Organisation (ISRO) and the Defence Research and Development Organisation (DRDO) play a pivotal role in fostering research and development in key areas such as avionics, artificial intelligence, and machine learning, which are rapidly transforming the aerospace sector.


Conclusion.

The Indian aerospace industry is on a transformative path, leveraging technology harvesting to bridge the gap between domestic capabilities and global standards. Through strategic partnerships, reverse engineering and indigenous R&D, India is steadily reducing its reliance on foreign suppliers. The success of projects like Tejas, AMCA, and hypersonic weapons development showcases India’s ability to absorb and innovate upon harvested technology. Further investments in jet engine technology, stealth aircraft, and AI-driven aerospace solutions will be key to solidifying India’s global power position. By strengthening its ecosystem through private sector participation and continued technology absorption, India is poised to achieve genuine self-reliance in aerospace and defence.


Please Do Comment.


2113
Default rating

Please give a thumbs up if you  like The Post?


Link to the article on the website:-

Technology Harvesting by Indian Aerospace Industry: A Strategic Imperative (by Air Marshal Anil Khosla)


For regular updates, please register your email here:-

Subscribe


References and credits

To all the online sites and channels.

Pic: Courtesy Net.

References:-

  1. “India’s Aerospace Industry: The Path Forward” (2021), by Aerospace and Defence Manufacturing Association of India (ADMA).
  1. “Atmanirbhar Bharat and the Indian Aerospace Industry” (2020), Ministry of Defence, Government of India.
  1. “The Indian Space Programme: An Overview” (2018), Indian Space Research Organisation (ISRO).
  1. Subramanian, K., & Iyer, R. (2022). “Technological Developments in India’s Aerospace and Defence Sector: Opportunities and Challenges.” International Journal of Aerospace Engineering, 35(4), 567-589.
  1. Sharma, S., & Dinesh, P. (2021). “The Role of Private Sector in Advancing Aerospace Technologies in India.” Asian Journal of Aerospace Technology, 27(2), 123-139.
  1. Aggarwal, M., & Kumar, A. (2020). “Defence Technology Development in India: The Next Frontier in Aerospace.” Journal of Defence Technology, 8(3), 220-233.
  1. “National Aerospace and Defence Policy Framework” (2019), Government of India.
  1. “Make in India: Aerospace and Defence” (2017), Department of Defence Production, Ministry of Defence, Government of India.
  1. “Aerospace & Defence Industry in India: An Overview” (2021), KPMG India.
  2. “Global Aerospace Outlook 2020” (2020), PwC India.
  1. “Indian Aerospace Industry: Key Trends and Future Potential” (2022), Ernst & Young India.
  1. “India’s Aerospace and Defence Sector is Taking Off” (2022), Economic Times.
  1. “How India’s Aircraft Manufacturers are Making Their Mark” (2021), The Hindustan Times.
  1. “Private Players Taking the Lead in India’s Aerospace Growth” (2020), Business Standard.

Disclaimer:

Information and data included in the blog are for educational & non-commercial purposes only and have been carefully adapted, excerpted, or edited from reliable and accurate sources. All copyrighted material belongs to respective owners and is provided only for wider dissemination.

603: Sequel to Previous Article on Rise of Combat Drones


My previous article, “Rise of Combat Drones: Implications for Traditional Air Power,” was well-received. The readers had a few queries and suggestions, which this sequel aims to address.


  1. Could you add a supplement or some riders, i.e., limitations in drone speed vis a vis the manned fighter, weapon loads that can be carried over such long distances, and what drones are available today that can overcome these liabilities?


Limitations in Drone Speed vs. Manned Fighters

Drones (Unmanned Combat Aerial Vehicles, or UCAVs) generally lag behind manned fighters in terms of speed due to several factors. One key reason is engine performance and design priorities. Most drones are optimised for endurance rather than speed, using turboprop or low-bypass turbofan engines for fuel efficiency. In contrast, manned fighters rely on high-bypass turbofans or afterburning turbojets, which provide the thrust needed for supersonic flight.

Aerodynamics also play a crucial role in speed limitations. Drones are typically designed for long loiter times and stealth, often requiring subsonic speeds and high-aspect-ratio wings to maximize efficiency. On the other hand, manned fighters prioritize agility, acceleration, and sustained speeds, especially in combat scenarios, where airframe designs enable them to reach speeds exceeding Mach 2.

Another significant factor is structural and cooling limitations. Supersonic flight generates extreme aerodynamic heating, necessitating the use of expensive thermal-resistant materials. Manned fighters incorporate robust cooling systems and heat-resistant materials to withstand these conditions. However, since most drones are optimised for cost efficiency and long-duration missions, they rarely include such features.

Command and control constraints also impact drone speed. The latency involved in remote control or autonomous decision-making can make high-speed operations risky. Pilots in manned aircraft can make split-second decisions during combat, whereas drones depend on AI algorithms or remote human operators, introducing potential delays that could be detrimental in high-speed engagements.


Weapon Load Considerations

Long-range drone missions face several challenges in carrying large weapon payloads. One primary limitation is structural capacity. Most drones are built for endurance and fuel efficiency rather than heavy payloads. For instance, the MQ-9 Reaper can carry about 1,700 kg of munitions, whereas an F-15E Strike Eagle can haul over 11,000 kg, demonstrating a significant gap in firepower.

Another issue is the trade-off between drag and fuel efficiency. Carrying heavy external ordnance drastically reduces a drone’s endurance, limiting its ability to remain in the air for extended periods. Additionally, stealth UAVs such as the RQ-170 Sentinel and B-21 Raider must carry weapons internally to maintain low observability, which further restricts payload volume compared to externally loaded fighter jets.

Drones also have limited air-to-air capabilities. Unlike manned aircraft, which can engage enemy fighters using a range of sophisticated air-to-air missiles, drones currently lack the manoeuvrability and situational awareness required for traditional dogfights. Some advanced UCAVs, like the MQ-28 Ghost Bat, are being developed with potential air combat roles, but their capabilities remain limited compared to manned fighters.


Drones Overcoming These Limitations

Despite these challenges, new drone designs are emerging to bridge the gap. Some high-speed drones are being developed to complement manned aircraft. The XQ-58A Valkyrie, which flies at Mach 0.85, is designed as a loyal wingman to assist fighters in combat. The RQ-180, a stealth drone reportedly in USAF service, is built for high-speed deep-penetration intelligence, surveillance, and reconnaissance (ISR) missions. A hypothetical but much-discussed concept, Darkstar, is believed to be a Mach 6+ reconnaissance drone, possibly inspired by the SR-72 project.

Several solutions exist for drones requiring greater payload capacity and endurance. The MQ-25 Stingray provides aerial refuelling, effectively extending the range of manned fighters. The B-21 Raider, while primarily a bomber, has the potential to take on UCAV roles. The RQ-170 Sentinel, a stealth reconnaissance drone, can perform deep-penetration missions without detection. Russia’s S-70 Okhotnik is another notable UCAV, heavily armed and designed to work alongside the Su-57 fighter.

Looking toward the future, Loyal Wingman drones such as the MQ-28 Ghost Bat and XQ-58A Valkyrie could supplement manned fighters in high-speed combat. Hypersonic drone concepts like the rumoured SR-72 could also revolutionise reconnaissance and strike capabilities, pushing drone technology toward greater autonomy and performance.


2. What’s the ballpark cost range of these drones?

The cost of military drones varies widely based on their size, capability, endurance, and payload.

(These approximate figures have been taken from open sources on the net and do vary)

Small Reconnaissance & Tactical Drones ($10,000 – $500,000). These drones are used for short-range surveillance, infantry support, and battlefield awareness. They are usually hand-launched or catapult-launched.

Drone Model Country  Approx. Cost
RQ-11 Raven USA $35,000 – $50,000 per unit
Switchblade 300 (loitering munition) USA $60,000 – $80,000
Skylark 3 Israel $100,000 – $300,000
Black Hornet Nano Norway $195,000 per system (includes multiple drones)


Medium-Altitude Long-Endurance (MALE) Drones ($1M—$20M). These drones are used for surveillance, reconnaissance, and precision strikes. They have higher endurance and often carry weapons.

Drone Model Country Approx. Cost
Bayraktar TB2 Turkey $5M – $7M per unit
MQ-1 Predator (Retired) USA $4M – $5M per unit
MQ-9 Reaper USA $15M – $30M per unit (depends on sensors & weapons)
Heron TP Israel $10M – $20M per unit
CAIG Wing Loong II China $2M – $5M per unit
Rustom-II / TAPAS India (DRDO) Estimated $4M – $6M per unit


High-Altitude Long-Endurance (HALE) Drones ($30M – $150M). These are strategic UAVs used for intelligence gathering, persistent surveillance, and deep strikes.

Drone Model Country Approx. Cost
RQ-4 Global Hawk USA $130M – $150M per unit
MQ-9B SkyGuardian USA $30M – $40M per unit
Heron Mk II Israel $20M – $25M per unit


Stealth & UCAVs (Over $50M). Unmanned Combat Aerial Vehicles (UCAVs) with stealth and advanced strike capabilities.

Drone Model Country Approx. Cost
XQ-58A Valkyrie USA $5M – $7M per unit
Ghatak UCAV (Under Dev) India Estimated $50M+
S-70 Okhotnik Russia $50M – $100M
nEUROn EU (Dassault) $50M – $80M


3. While India is developing drones rapidly, what’s holding it back from matching, say, the Turks?

India has made some progress in drone technology, but it’s still behind countries like Turkey, which has established itself as a major drone power with combat-proven UAVs. The main factors holding India back include:-

Gaps in Indigenous R&D and Manufacturing. India’s drone development is largely led by state-owned entities like DRDO, which tend to be slower and less agile than private companies. Turkey has Baykar (Bayraktar TB2, Akıncı) and TAI (Anka, Aksungur), which are aggressive in R&D, production, and exports. Indian private companies are entering the UAV space, but they lack the scale and experience of Turkish firms.

Engine and Sensor Technology Dependence.  India relies on foreign engines for its drones. For example, the indigenous Rustom UAV uses an Austrian Rotax 914 engine. Turkey has worked around this by producing engines (e.g., TEI PD-170 for Anka UAVs). High-end sensors and satellite communication technology are also areas where India still depends on imports.

Delayed and Overregulated Procurement. India’s defence procurement process is bureaucratic and slow, with lengthy approvals, trials, and acquisition delays. The focus on “Make in India” sometimes results in delays when indigenous solutions are pushed over faster foreign acquisitions.

Lack of a Dedicated Drone Warfare Doctrine. While India has UAVs for surveillance and reconnaissance, it lacks a coherent doctrine for using armed drones in combat. On the other hand, Turkey has developed UAV-centric warfare concepts, integrating drones with air and ground operations.

Combat Experience and Export Focus. Turkey has extensively tested its drones in combat (Syria, Libya, Nagorno-Karabakh, Ukraine), refining them in real-world scenarios. India lacks such experience, as its military engagement with drones has been limited (primarily surveillance against Pakistan and China). Turkey has aggressively exported drones (to over 30 countries), which helps fund further R&D. India is only now entering the export market.

Lesser Political Will for UAV-centric Warfare. Turkey’s political leadership (especially under Erdoğan) has strongly backed UAV development, using it as a strategic tool for geopolitical influence. India, while investing in UAVs, still prioritises manned aircraft and traditional military assets over a full-fledged drone warfare strategy.

India is trying to catch up.

  • Indigenous UAVs like Tapas (Rustom-II), Archer-NG, and Ghatak stealth UCAV are being developed.
  • India has acquired MQ-9B Reapers from the US for enhanced strike capability.
  • Private sector involvement is increasing, with startups focusing on AI-powered drones, loitering munitions, and swarm technology.
  • India is pushing for exports, with countries like Armenia and Southeast Asian nations showing interest in Indian UAVs.


4. What’s the risk of drones escalating warfare? If we and our western neighbor both deploy surveillance drones and start shooting them down, will it increase tensions?

Yes, the deployment of drones—especially if both India and Pakistan engage in shooting them down—can escalate tensions in several ways. While drones reduce the risk to human pilots, they also lower the threshold for conflict by making military engagement seem less costly or provocative at first.

Increased Risk of Tit-for-Tat Escalation. If both countries start shooting down each other’s drones, it could trigger a cycle of retaliation. A drone being shot down is not the same as a manned aircraft loss, but it still represents an attack on sovereign military assets. If both nations were to lose expensive UAVs repeatedly, military pressure to respond would increase.

Ambiguity and Miscalculation. Surveillance drones operate near sensitive borders, making distinguishing between a reconnaissance UAV and a strike-capable drone hard. A country may shoot down a drone assuming it is armed, escalating tensions unnecessarily. The U.S. and Iran have had multiple drone-related incidents, with Iran shooting down a U.S. RQ-4 Global Hawk in 2019, nearly leading to a retaliatory strike.

Crisis Instability and Automated Retaliation. If both sides deploy AI-assisted drone swarms or automated defensive systems, it could lead to uncontrolled escalation. A drone automatically targeting an enemy UAV or launching a retaliatory strike could trigger a rapid, unintended military response. The Armenia-Azerbaijan conflict saw drones targeting command centres—a dangerous precedent if similar attacks happen in South Asia.

Psychological & Political Pressures. The public might demand retaliation for a downed UAV, just as it would for a manned aircraft. With drones capturing and transmitting live footage, propaganda battles could fuel public anger, pushing governments toward escalation. If a drone is shot down over disputed territory and its footage is released, political and military leaders may feel pressure to respond forcefully.

Drone warfare makes escalation more likely because it removes the human cost, making military engagements seem less risky. However, once UAV shootdowns become frequent, the pressure to retaliate more aggressively could lead to conventional military strikes or full-scale escalation. In the India-Pakistan context, drone warfare—if not carefully managed—could become a dangerous flashpoint.


5. Till now drones have been employed successfully against a technologically weaker adversary and reducing direct exposure of combatants to the enemy fire. It is difficult to predict the outcome when both contestants have similar capabilities.

When both contestants possess similar drone capabilities, predicting the outcome of a conflict becomes exceedingly complex as technological parity shifts the focus toward strategic, tactical, and logistical factors. The effectiveness of drones in battle is not solely determined by their specifications but by how well they are integrated into broader warfare systems. Electronic Warfare (EW) superiority plays a decisive role, as the side with more advanced jamming, spoofing, or cyber capabilities can disrupt enemy drone operations, rendering them ineffective. Integration with broader military assets is equally crucial; drones do not function in isolation but work alongside air defence. Coordinating drone reconnaissance with precision strikes or air defence suppression can significantly influence the battlefield. Moreover, operational doctrine determines how drones are deployed—whether used in swarms to overwhelm defences, prioritised for ISR (intelligence, surveillance, and reconnaissance), or focused on Suppression of Enemy Air Defences (SEAD). Even with comparable drone technology, the side that adapts its doctrine more effectively to the battlefield conditions will have the upper hand. Lastly, logistics and sustainability are often overlooked but are critical to long-term drone warfare. Given the high attrition rate of drones, the ability to rapidly replace lost UAVs, maintain a steady supply of spare parts, and ensure uninterrupted operations becomes a decisive factor. A country with a well-developed domestic production line and efficient supply chain will have a sustained advantage over one dependent on imports or struggling with manufacturing constraints. When both sides have similar drone capabilities, victory does not merely hinge on superior technology but on how effectively drones are employed, defended, and resupplied in the face of constant attrition and evolving battlefield challenges.


6.  Cost vs benefit could impose a limit. 


Cost vs. Benefit Analysis of Drone Warfare

Drone warfare has transformed modern military operations, offering strategic advantages and introducing new risks and costs. Below is a structured cost-benefit analysis considering various aspects of drone warfare.

Cost-Benefit Comparison: Drone vs. Manned Combat Systems

Factor Drones Manned Aircraft/Troops
Cost per Unit Low High
Operational Cost Low High
Survivability Low High
Effectiveness in Asymmetric Warfare High Moderate
Electronic Warfare Vulnerability High Low
Risk to Human Life None High
Strategic & Psychological Impact High Moderate

Drone warfare offers a high return on investment, particularly in asymmetric conflicts and precision strikes. However, drones remain vulnerable in high-intensity warfare against near-peer adversaries and require integration with traditional military assets to stay effective. While they provide cost-effective alternatives to manned aircraft, the rapid evolution of counter-drone technology will ultimately determine their long-term viability on the battlefield.


7. Terrain and sensor limitations could impose a challenge. 

While drones offer significant advantages in modern warfare, they face critical terrain and sensor effectiveness challenges. These limitations can impact reconnaissance, targeting, and overall combat efficiency. 


Challenges to Drone Warfare Due to Terrain.

Mountains and Rugged Terrain. Mountainous regions pose several challenges for drone operations. Signal disruptions occur due to steep terrain blocking radio waves, which affects real-time control and data transmission. Additionally, drones rely on line-of-sight (LOS) sensors, such as optical and infrared cameras, which struggle to track targets moving through valleys, caves, and ridges. Wind and air pressure variability in high-altitude areas cause strong turbulence, making drone operation difficult. Furthermore, reduced endurance at high altitudes forces drones to consume more energy to maintain flight, limiting loiter time and operational efficiency. In Afghanistan, U.S. drones had difficulty tracking Taliban fighters who used caves and rugged terrain to evade detection, requiring ground forces and satellites for confirmation.

Dense Forests and Jungles. Drones face significant vision obstruction in dense foliage, reducing the effectiveness of optical, infrared, and LIDAR sensors. High humidity and weather interference in jungles can degrade drone electronics and infrared imaging, reducing reliability. Additionally, drones struggle to locate small or camouflaged units as guerrilla fighters blend into thick vegetation. In a Vietnam War-style scenario, drones would struggle to track Viet Cong-like guerrilla fighters moving under jungle cover, limiting their effectiveness in counterinsurgency.

Urban Warfare Challenges. Urban environments introduce GPS signal interference, as high-rise buildings cause multipath errors that reduce navigation accuracy. Limited sensor coverage in narrow streets and indoor hideouts makes tracking enemy movements difficult. Higher risks of collateral damage require extreme precision in drone strikes to avoid civilian casualties. Moreover, urban areas provide cover for electronic warfare (EW) units that can jam or spoof drone signals. In Gaza and Mosul, drones have been effective but struggled with hidden tunnels, EW disruptions, and difficulty distinguishing combatants from civilians.

Desert and Open Plains. Drones operating in deserts face extreme heat and dust storms, which degrade battery performance and reduce sensor visibility. Additionally, the lack of cover in open plains makes drones easier targets for air defence systems. Thermal imaging is also affected, as high infrared signatures from sand make distinguishing human targets from the environment difficult. In Libya and Syria, drones were less effective during sandstorms, limiting their ability to track mobile convoys.


Challenges to Drone Warfare Due to Sensor Limitations

Optical and Infrared Sensor Issues. Drones rely on optical and infrared sensors, but these are affected by weather conditions such as clouds, fog, smoke, and rain, which degrade visibility. Camouflage and deception techniques, including heat-reflecting blankets and decoys, can further confuse infrared sensors. While infrared and thermal imaging assist in night time operations, they still face limitations in extreme cold or cluttered environments. Russian forces in Ukraine have successfully used smoke screens and camouflage nets to evade drone detection.

Radar and LIDAR Limitations. Radar and LIDAR sensors face constraints in complex environments. Limited ground penetration makes it difficult to detect underground bunkers and tunnels. In urban environments, signal reflection and distortion cause errors in target identification. Additionally, low-flying drones use active radar risk detection by enemy air defences. Hamas tunnels in Gaza remain challenging to detect despite drone surveillance due to their underground depth and deceptive entry points.

Electronic Warfare (EW) & Cyber Security Vulnerabilities. Drones are vulnerable to jamming, which disrupts communication links with operators. Spoofing and hacking techniques can mislead drones into incorrect locations or even hijack them. Advanced EMP and directed energy weapons can disable drones using electromagnetic pulses or lasers. In Ukraine, Russian EW systems have jammed and downed thousands of drones, forcing Ukrainian operators to develop alternative navigation methods.


While terrain and sensor limitations challenge drone effectiveness, technological innovations gradually overcome these barriers. Drones’ success in future conflicts will depend on their adaptability, resilience against electronic warfare, and integration with other military assets. As adversaries continue developing counter-drone measures, drone warfare will evolve in response, ensuring that UAVs remain a dominant force in modern combat.


Please Do Comment.

2113
Default rating

Please give a thumbs up if you  like The Post?


For regular updates, please register your email here:-

Subscribe


References and credits

To all the online sites and channels.


Disclaimer:

Information and data included in the blog are for educational & non-commercial purposes only and have been carefully adapted, excerpted, or edited from reliable and accurate sources. All copyrighted material belongs to respective owners and is provided only for wider dissemination.


English हिंदी